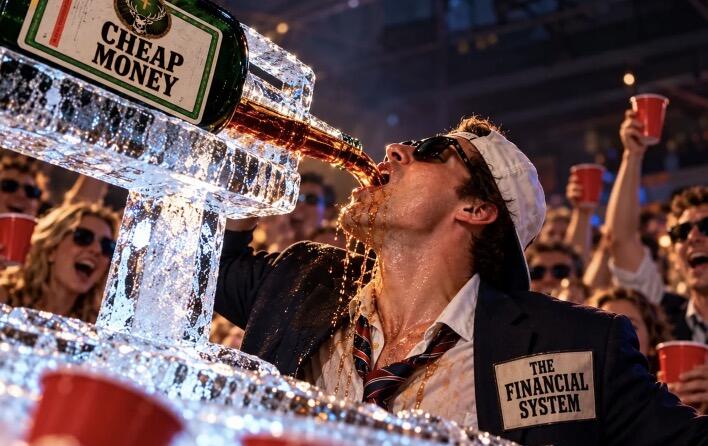
End of the Cheap-Money Era: US Debt Hits $40T Amid AI Valuation Reckoning and Market Selloff
Corroborated by Treasury data and mainstream reporting, the ZeroHedge thesis on ending financial delusion aligns with $40T+ US debt, $2T deficits, AI-driven leverage concerns, and October 2026 market turbulence from rising yields and inflation. This points to a structural market recalibration rather than isolated volatility.
The United States national debt has surpassed $40.3 trillion as of early October 2026, with the fiscal 2026 deficit reaching nearly $2 trillion—the largest in five years outside of pandemic-era spikes—driven by record interest payments exceeding $1.36 trillion and sustained spending on entitlements and defense.[1][2] Official Treasury data and analyses from Reuters and the Committee for a Responsible Federal Budget confirm annual borrowing near $2 trillion, with debt held by the public approaching GDP levels.[3][4]
This backdrop coincides with a sharp October 2026 equity selloff, particularly in AI-linked technology stocks. Bloomberg and Reuters reported an eight-session rout in semiconductors, with Asia's chipmakers (e.g., Samsung, SK Hynix) plunging amid concerns over trillions in borrowed capital for AI infrastructure, higher financing costs, and doubts about near-term returns.[5][6] Hotter-than-expected inflation data fueled fears of sustained higher rates, pressuring valuations built on low-cost leverage. The Guardian noted IMF warnings about AI share-price risks to global stability.[7]
Rising Treasury yields, with 10-year notes exceeding 5% for the first time in decades, have acted as a 'wood chipper' for rate-sensitive assets and highly leveraged bets, echoing longstanding critiques of normalized financial excess. Motley Fool and BlackRock analyses highlight how elevated yields erode appeal of growth stocks while exposing corporate borrowing for AI capex, buybacks, and private credit.[8][9] Moody's reports underscore hidden stresses in private credit, where broader distress metrics (including PIK amendments) exceed reported defaults.[10]
Wall Street complacency—evident in downplaying systemic debt risks—has left investors psychologically exposed as markets confront the limits of two decades of accommodative policy. The selloff signals a potential shift toward scrutiny of theoretical AI returns versus real borrowing costs, with broader implications for leveraged finance and fiscal sustainability.
[LIMINAL]: Persistent high debt and AI leverage scrutiny will accelerate rotation out of crowded growth trades into value and income assets, pressuring policy responses on fiscal restraint.
Sources (7)
- [1]Debt to the Penny | U.S. Treasury Fiscal Data(https://fiscaldata.treasury.gov/datasets/debt-to-the-penny/)
- [2]US annual budget gap hits nearly $2 trillion, largest in 5 years | Reuters(https://www.reuters.com/world/us/us-fiscal-2026-budget-deficit-rises-199-trillion-largest-5-years-2026-10-16/)
- [3]U.S. Budget Deficit Nears $2 Trillion, a Reality Check for Trump’s Cost Cutting - The New York Times(https://www.nytimes.com/2026/10/16/business/us-budget-deficit.html)
- [4]AI Trade Reversal Pierces Asia’s Star Picks-and-Shovels Stocks - Bloomberg(https://www.bloomberg.com/news/articles/2026-10-18/ai-trade-reversal-pierces-asia-s-star-picks-and-shovels-stocks)
- [5]Global hedge funds hammered by AI selloff this week, Asia managers lead losses | Reuters(https://www.reuters.com/world/china/ai-selloff-hammers-hedge-funds-this-week-asia-managers-lead-losses-2026-10-16/)
- [6]Moody’s Says Private Credit Stress Is Worse Than Default Rates Suggest - Benzinga(https://www.benzinga.com/markets/private-markets/26/10/62406062/moodys-finds-private-credit-stress-is-worse-than-default-rates-suggest-warns-of-maturity-wall)
- [7]The Bond Market Just Reached a Dangerous Milestone. Here's What It Means for Stock Investors. | The Motley Fool(https://www.fool.com/investing/2026/10/14/bond-market-dangerous-milestone-stock-invest/)