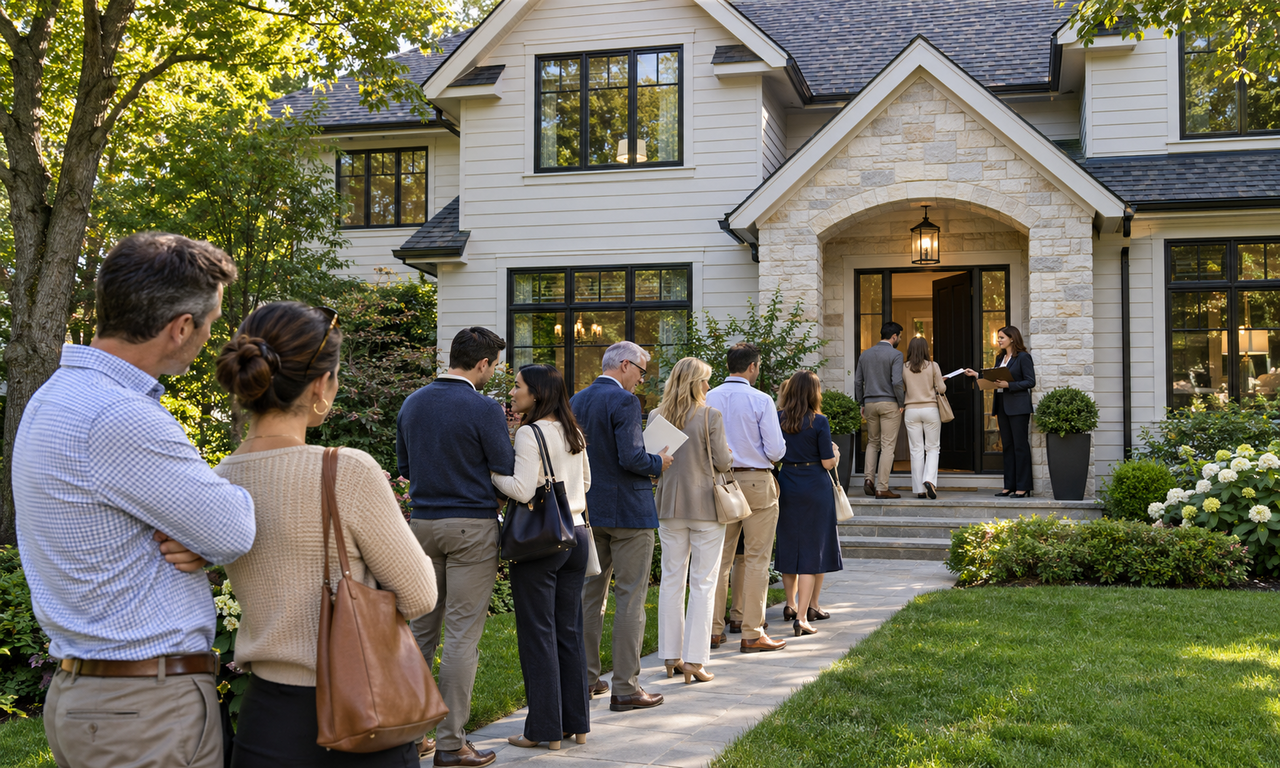
Long Island remains a seller's market with cash bids losing out as national pending home sales hit a record low
NAR's pending-home-sales index hit a record low in September as mortgage rates rose, while Redfin still ranks Nassau–Suffolk as the strongest seller's market among large U.S. metros, with local medians at records and listings scarce.
Documented: Contracts to buy existing U.S. homes fell sharply in September. The National Association of Realtors' Pending Home Sales Index dropped 7.3% to 66.0, the lowest reading since the series began in 2001, and was down 11.3% from a year earlier, according to NAR figures reported by Reuters, HousingWire, and Dow Jones. NAR chief economist Lawrence Yun attributed the drop to fast-rising mortgage rates, saying buyers and sellers may be holding back until rates move favorably. All four regions declined; the Northeast fell 4.2% on the month, less than the West, South, and Midwest.
Documented, and in the opposite direction: Nassau County, New York—which in Redfin's metro definition covers Nassau and Suffolk counties on Long Island—has repeatedly ranked as the country's strongest seller's market even as most large metros have tilted toward buyers. Redfin's October 2026 buyers-versus-sellers report, published the same day as a New York Post account of local bidding wars, found only three of the 50 largest metros still favored sellers, the fewest since the pandemic freeze of April 2020. Nassau led that short list, with an estimated 24.7% fewer sellers than buyers, down from a 28.3% gap in September. Earlier in the year the gap was wider: Newsday reported Redfin's July estimate of buyers outnumbering sellers by 36.2% (about 11,958 buyers versus 7,631 sellers), and a January Newsday report cited a November figure of about 39.1% fewer sellers than buyers. Nationally, Redfin estimated 70.5% more sellers than buyers in October, the widest gap in records back to 2013.
Claimed, in reporting by the New York Post and not independently verified in public transaction records here: retired orthopedic surgeon Frank DiMaio said he and his wife lost a Woodbury townhouse after a $2.3 million offer on a $2.4 million listing was accepted, paperwork was signed, and a $230,000 deposit was wired, only for the sellers to walk away for another offer before signing. The Post reported the couple later bought a renovated Oyster Bay home listed at $1.99 million for $2.1 million after a full-price offer drew no response. Agent David Cohen of Corcoran SRG Residential, quoted by the Post, described the listings as largely recycled inventory. Those anecdotes illustrate a pattern that local listing data already show; they do not, by themselves, measure how often all-cash buyers lose.
Documented local prices and supply: OneKey MLS figures reported by Newsday and Long Island Business News put the August median closed sale at a record $911,000 in Nassau (up 4.7% from a year earlier) and a record $760,000 in Suffolk (up 7%). Pending contracts and closed sales were lower than a year earlier even as prices rose. Inventory remained far below pre-pandemic levels. Appraiser Jonathan Miller, cited by Newsday, said more than half of Long Island sales outside the East End closed above the last asking price and that the competition is not confined to luxury buyers. Moody's Analytics economist Adam Kamins, also cited by Newsday, said Long Island's price gains have outpaced the country mainly because too few owners are willing to sell, not because demand is unusually large relative to the rest of the U.S.
What is documented, then, is a split market, not a single national freeze with one unexplained bubble on top. National contract activity is at a series low as mortgage rates rise. A handful of Northeast metros, led by Nassau–Suffolk, still have more estimated buyers than sellers. Local analysts tie that imbalance to scarce listings, limited land, and owners holding mortgages taken out at much lower rates. Speculated, and not shown by the sources above: that the Long Island premium is evidence of a separate speculative credit bubble or of imminent systemic financial fragility. The published data describe price records alongside thin inventory and a national contract collapse; they do not document rising distress, widespread cash-only financing, or a break in local credit conditions.
Buyers on Long Island are still competing for a thin supply of homes, including with cash, while contract signings nationwide have fallen to the lowest level NAR has recorded. Owners sitting on older, cheaper mortgages are a documented reason listings stay scarce, which keeps local prices at records even as the national market cools.
Sources (6)
- [1]US pending home sales tumble to record low in September(https://www.reuters.com/business/us-pending-home-sales-tumble-record-low-september-2026-10-20/)
- [2]NAR pending home sales index falls to record low in September(https://www.housingwire.com/articles/pending-home-sales-record-low/)
- [3]Just 3 Major U.S. Metros Are Seller’s Markets—the Fewest Since the Pandemic Freeze(https://www.redfin.com/news/buyers-vs-sellers-october-2026)
- [4]Bidding wars for Long Island homes are so brutal, even all-cash buyers are getting burned(https://nypost.com/2026/11/12/real-estate/long-island-is-americas-toughest-housing-market-to-crack/)
- [5]Long Island home prices surge to record highs in August(https://www.newsday.com/real-estate/long-island-home-prices-august-2026-kjvcum7o)
- [6]Higher mortgage rates, prices make for challenging fall for Long Island homebuyers(https://www.newsday.com/real-estate/buying-selling-house-fall-long-island-hstab7pv)