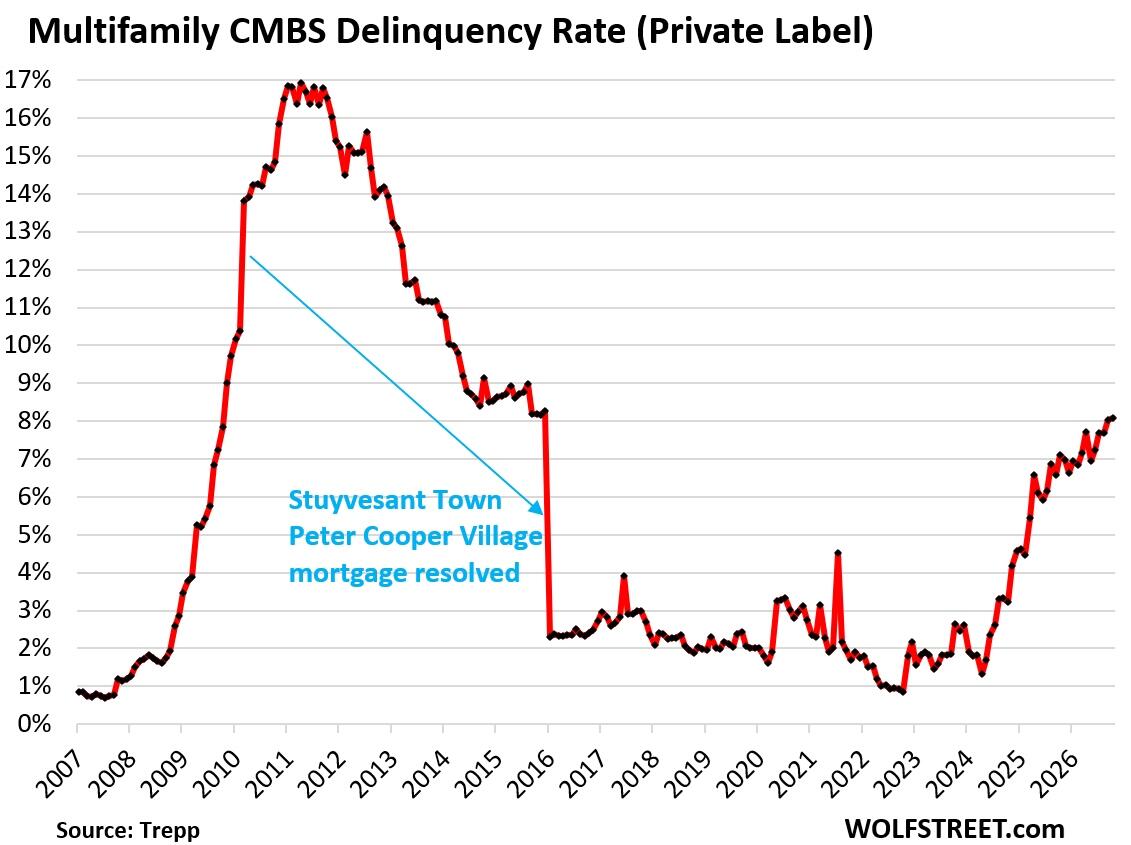
Multifamily CRE Distress Deepens: CMBS Delinquencies Near 8.1% Amid Refinancing Strain and GSE Exposure
Corroborated reports confirm escalating multifamily CRE delinquencies near 8.1%, with high-profile defaults at The Cove at Tiburon and The Beaudry highlighting refinancing failures and $1.2T GSE exposure.
Multifamily commercial real estate loans total approximately $2.3 trillion, with Fannie Mae and Freddie Mac holding about $1.2 trillion—half the market—exposing taxpayers to substantial risk as defaults mount. Recent data from the Mortgage Bankers Association confirms multifamily mortgage debt reached $2.3 trillion in Q2 2026, with agencies accounting for 50% of holdings.
CMBS multifamily delinquency rates have climbed to around 8.04-8.09% in September-October 2026 per Trepp reports, the highest levels in years and driven by maturity defaults on loans originated at ultra-low rates. This marks a sharp rise from sub-7% readings earlier in the cycle, with private-label CMBS bearing a disproportionate share of distress despite representing a smaller portion of the market.
Specific cases underscore the pressure. The $210 million interest-only loan on The Cove at Tiburon, a 283-unit Class A waterfront property in Marin County, CA, entered special servicing after failing to refinance at maturity; it had been modified in November 2025 but faces declining occupancy (around 80% in 2024 rent rolls) and cash flows insufficient for current rates. Morningstar DBRS and CRE Direct have tracked the loan's watchlist status and extension negotiations.
Similarly, Brookfield has surrendered The Beaudry, a 785-unit luxury tower in downtown Los Angeles developed for $600 million and opened in 2023. The $360 million loan held by Apollo's Bridge Investment Group cannot be refinanced economically; the lender is now marketing the debt while the property sits at ~95% occupancy but below original rent targets amid downtown market challenges.
These incidents reflect broader patterns: higher interest rates, SOFR-linked variable debt, and maturing balloons from 2020-2021 originations are forcing 'extend and pretend' strategies or workouts. Agency loans show lower but rising delinquencies, while overall CRE debt maturities loom large through 2030.
Sources (6)
- [1]Multifamily CMBS delinquency and servicing rates rose yet again(https://www.multifamilydive.com/news/cmbs-servicing-federal-reserve-apartment-deliquency/833363/)
- [2]Multifamily CMBS delinquency rate continues rise in October(https://yieldpro.com/2026/11/multifamily-cmbs-delinquency-rate-continues-rise-in-october/)
- [3]Morningstar DBRS Confirms Credit Ratings on SG Commercial Mortgage Securities Trust 2020-COVE(https://dbrs.morningstar.com/research/467670)
- [4]Brookfield Surrenders Downtown’s Beaudry Residential Tower(https://therealdeal.com/la/2026/11/03/brookfield-surrenders-downtowns-beaudry-residential-tower/)
- [5]Commercial and Multifamily Mortgage Debt Outstanding Increased by $42.9 Billion in Second-Quarter 2026(https://www.mba.org/news-and-research/newsroom/news/2026/09/29/commercial-and-multifamily-mortgage-debt-outstanding-increased-by--42.9-billion-in-second-quarter-2026)
- [6]CMBS Delinquency Falls to 7.87%, Office Hits 12.33%(https://www.credaily.com/briefs/cmbs-delinquency-rate-dips-to-7-87-as-retail-jumps-63-bps/)