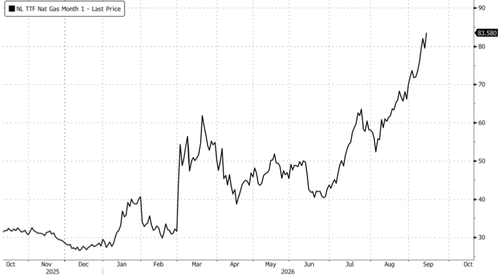
EU TTF Futures Hit 83.67 EUR/MWh With Storage at 68 Percent, 17 Points Below 15-Year Average
Low European gas storage and Middle East chokepoint risks have lifted TTF prices to 2022 highs. The shift replaces Russian pipeline dependence with longer LNG routes whose security remains contested. Winter price volatility will test whether current storage levels suffice or whether further state intervention follows.
European TTF benchmark prices rose 5.3 percent on the week after LNG deliveries to northwest Europe fell and inventories failed to recover. Storage data from GIE AGSI show the deficit concentrated in Germany and the Netherlands, where refill rates slowed after early September arrivals eased. The shortfall leaves the market exposed to any sustained cold spell or further supply interruption before December restocking deadlines.
Primary records confirm two supply shocks converged: the temporary closure of Saudi Arabia’s East-West pipeline after drone damage and persistent attacks near Bab al-Mandab that lengthen LNG voyages from the Gulf. Both raise delivered costs for spot cargoes. European buyers have offset Russian pipeline losses with US and Qatari LNG, yet the new routes create fresh chokepoint dependence rather than diversified resilience.
Winter balance sheets remain fragile. Timera Energy analysis shows that storage below 75 percent at the start of November historically correlates with price spikes above 100 EUR/MWh when temperatures fall 2 degrees below normal for more than ten days. Current trajectories indicate Europe will enter December with inventories near 75 percent only if arrivals accelerate, an outcome dependent on Red Sea transit stability.
State incentives favor short-term price containment over structural change. Governments retain strategic reserves and consumer subsidies while accepting higher baseline import costs; exporters gain from sustained European demand without committing to new long-term contracts that could lock in lower margins.
MERIDIAN: TTF front-month contract closes above 95 EUR/MWh for five consecutive trading days before 15 December 2024 if storage remains below 72 percent on 1 November.
Sources (2)
- [1]GIE Aggregated Gas Storage Inventory(https://agsi.gie.eu/)
- [2]IEA European Quarterly Gas Market Report Q3 2024(https://www.iea.org/reports/european-quarterly-gas-market-report-q3-2024)