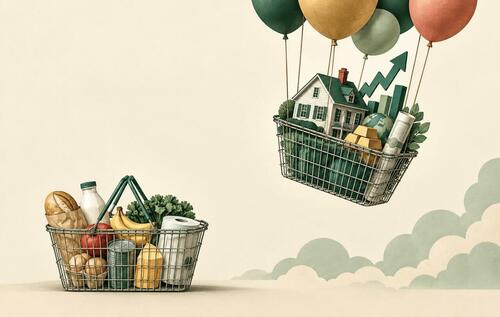
CPI Excludes Asset Prices as M2 Growth Exceeds Real GDP and Consumer Inflation by 1.2 Points Annually Since 1995
The CPI’s theoretical exclusion of asset prices has concealed the largest component of price growth since 1995, driven by a persistent monetary overhang. Data from M2, Case-Shiller, and S&P returns show this gap compounds into measurable wealth stratification that official cost-of-living adjustments do not register. The structure remains unchanged despite the scale of the distortion.
The Bureau of Labor Statistics constructs the CPI on the basis of Haberler’s 1927 index-number framework, which assumes a pure consumer holding no portfolio or investment property. Owners’ equivalent rent captures only imputed shelter services, leaving the Case-Shiller national home price index and S&P 500 total returns outside the measure the Federal Reserve targets via PCE. Since 1995 the S&P 500 has compounded at 9.2 percent and homes at 4.7 percent against CPI’s 2.6 percent, a divergence that widened precisely when annual M2 growth exceeded the sum of real GDP and CPI growth by 1.2 points.
Cantillon effects explain the pattern: new liquidity enters through credit markets and reaches asset holders first. Pre-1995 M2 growth trailed the combined benchmark by one point; the post-1995 reversal produced a persistent monetary overhang absorbed by equities and real estate rather than consumer goods. Younger households without prior holdings face higher entry prices while the index used for COLAs and policy remains unchanged.
The exclusion is not neutral. It sustains the documented renter-owner wealth gap at record levels and masks the portion of inflation transmitted through balance-sheet channels rather than the goods basket. Primary records from the Federal Reserve’s H.6 release and BLS CPI methodology confirm the accounting treatment has remained consistent while the scale of the omitted component has grown.
Continued M2 expansion above the combined benchmark will compound the divergence unless asset valuations correct or the index framework is revised to incorporate portfolio costs.
Federal Reserve: M2 growth will remain above the sum of real GDP and CPI by at least 0.8 points through Q4 2026, sustaining the asset-CPI divergence.
Sources (3)
- [1]Bureau of Labor Statistics CPI Handbook of Methods(https://www.bls.gov/cpi/methodology.htm)
- [2]Federal Reserve H.6 Money Stock Measures(https://www.federalreserve.gov/releases/h6/)
- [3]S&P Dow Jones Indices S&P 500 Factsheet(https://www.spglobal.com/spdji/en/indices/equity/sp-500/)