CoreWeave's $76-85B Funding Gap Spotlights Neocloud Debt Risks Amid AI Buildout
Bernstein's analysis of CoreWeave's multi-billion-dollar funding shortfall amid high-yield debt and capex demands highlights risks for neoclouds and AI investors, potentially driving consolidation as financing costs rise.
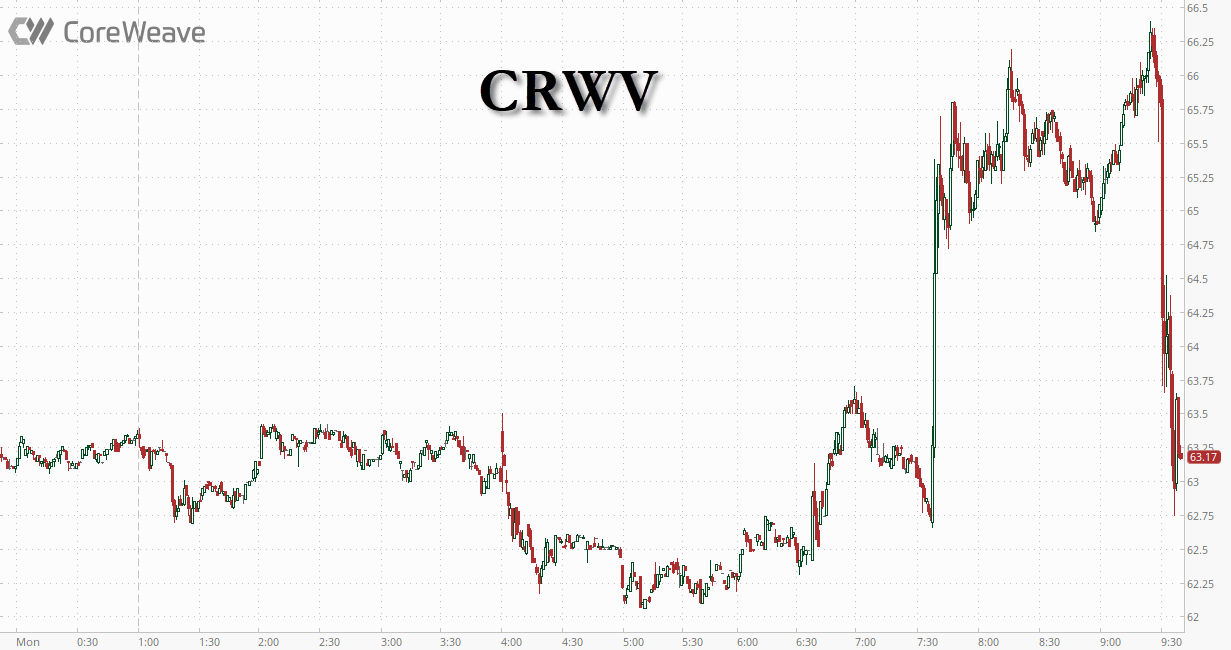
Bernstein analyst Madison Rezaei has highlighted a substantial financing shortfall for CoreWeave (CRWV), estimating the company needs roughly $85 billion to fund its existing customer backlog, with only about $9 billion covered by current facilities—leaving an approximately $76 billion hole that must be bridged through additional capital. This assessment, reiterated in recent notes cutting the price target to $51 while maintaining an Underperform rating, underscores the capital-intensive nature of neocloud operations, where specialized AI cloud providers like CoreWeave lease data centers, borrow heavily to acquire GPUs, and generate revenue from contracts. CoreWeave carries around $35-50 billion in debt and $16.5 billion in lease liabilities, with unsecured bonds yielding near 15% (e.g., 9.625% notes due 2032 trading at distressed levels), signaling expensive future borrowing. The company reported a Q2 net loss of $626 million alongside $679 million in operating cash flow against $9.4 billion in adjusted capex, with net interest expense at $640 million. A large contracted backlog—$104 billion as of June, later exceeding $129 billion—provides demand visibility, including commitments from hyperscalers and AI firms, yet analysts note that high financing costs and shorter-duration contracts could erode equity returns. Reuters and other outlets have framed CoreWeave as emblematic of broader AI infrastructure debt concerns, with credit default swaps implying elevated default risk and insurers/Gartner highlighting vulnerabilities for neoclouds. Bernstein views the risk as potentially semi-contained, suggesting colo contracts could be absorbed if CoreWeave faltered, while contrasting views from BofA (Buy rating, $140 target, lower ~$20B gap estimate) reflect ongoing debate. Goldman Sachs recently upgraded to Buy despite trimming targets. These pressures may accelerate industry consolidation or restructuring among neoclouds, as Gartner projects up to 80% could cease independent operations by 2030 amid unsustainable capex relative to demand timelines. Nvidia's backstop for unsold capacity through 2032 offers some support but does not resolve core refinancing challenges. For investors, the episode signals heightened scrutiny on AI debt-fueled expansion, with potential ripple effects on private credit and broader tech valuations.
Bernstein: CoreWeave's financing challenges represent a contained but illustrative risk for the neocloud sector, likely prompting selective consolidation rather than systemic AI market disruption.
Sources (6)
- [1]CoreWeave Stock (CRWV) Sinks as Bernstein Warns of an $85 Billion Funding Problem(https://www.tipranks.com/news/coreweave-stock-crwv-sinks-as-bernstein-warns-of-an-85-billion-funding-problem)
- [2]CoreWeave's slump spotlights growing burden of debt behind AI boom(https://www.reuters.com/legal/transactional/coreweave-shares-bonds-slide-further-ai-debt-fears-mount-2026-10-15/)
- [3]CoreWeave continues to decline, but Bernstein contends it hasn't hit bottom yet(https://seekingalpha.com/news/4655980-coreweave-continues-to-decline-but-bernstein-contends-it-hasnt-hit-bottom-yet)
- [4]Bernstein keeps CoreWeave at Underperform, $74 target as bond yields near 15%(https://blockspace.media/insight/coreweave-bond-yields-underperform-target/)
- [5]Bernstein and BofA Clash Over CoreWeave's Funding Gap(https://www.ad-hoc-news.de/boerse/news/unternehmensnachrichten/bernstein-and-bofa-clash-over-coreweave-s-funding-gap-as-product-push-takes-a-back-seat/70395006)
- [6]Why CoreWeave is in the crosshairs of the AI scare(https://www.reuters.com/legal/transactional/why-coreweave-is-crosshairs-ai-scare-2026-10-16/)