Franklin Templeton Warns of Eurozone Debt Crisis 2.0 as French Bond Spreads Hit Multi-Year Highs
Credible financial and market sources corroborate Franklin Templeton's warning of elevated risks for a severe eurozone debt crisis triggered by France's deteriorating finances and bond market stress, with spreads at crisis-era levels and yields near multi-decade highs.
Major asset manager Franklin Templeton has issued a stark warning that markets are unprepared for a potential new euro-area sovereign debt crisis centered on France, one that could prove more severe than the 2010-2012 turmoil. In recent comments, Sonal Desai, the firm's chief investment officer for fixed income, highlighted that France's public debt exceeds Greece's by more than tenfold at the onset of the prior crisis, rendering a simple bailout unfeasible. "I don't think anyone is really ready for a euro-zone debt crisis version 2.0," Desai stated, adding that this iteration "could be significantly worse."[1][2]
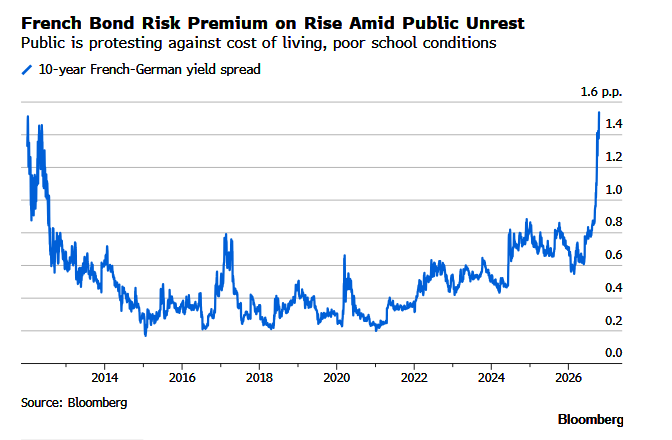
Market data supports the urgency. French 10-year government bond (OAT) yields have climbed toward or briefly exceeded 5%, levels unseen since 2002, while the spread over German Bunds widened to around 150-159 basis points in October 2026—the widest since the height of the euro crisis.[3][4] This reflects investor demands for higher premiums amid France's fiscal deficits, political gridlock ahead of 2027 elections, and social unrest including protests that have pressured the government. Reuters and Bloomberg reported ongoing volatility, with French yields leading eurozone moves higher amid energy price spikes and budget concerns.[5]
Broader context reveals structural vulnerabilities: France's debt-to-GDP ratio hovers near 119-120%, with persistent deficits and limited fiscal space compared to smaller peripherals in 2012. ECB Governing Council members have stressed deficit control for debt sustainability, while analysts note contagion risks to Italy and others, though some view it as France-specific so far.[3][6] Institutional investors like those at Franklin Templeton, Pimco, and Vanguard have signaled reduced appetite for French debt. US officials have downplayed immediate spillovers, but the episode underscores how bond markets can discipline large eurozone economies lacking unified fiscal backstops.
Deeper connections emerge when linking fiscal strain to political polarization and protest dynamics, amplifying market repricing. Unlike 2012, today's environment features higher global yields and greater investor choice among euro assets, potentially accelerating volatility. While no full crisis has materialized, the warnings highlight risks to stability, borrowing costs, and growth if deficits remain unchecked.
Market Analyst: Persistent French fiscal and political pressures could sustain elevated bond volatility into 2027, pressuring eurozone policy coordination and investor portfolios exposed to peripheral debt.
Sources (5)
- [1]Franklin Templeton avisa a Europa y al BCE(https://www.eleconomista.es/mercados-cotizaciones/noticias/14022442/10/26/franklin-templeton-avisa-a-europa-y-al-bce-la-crisis-de-francia-puede-ser-considerablemente-peor-que-la-de-2012-y-hay-una-razon-de-peso-para-creerlo.html)
- [2]France’s debt troubles stir memories of the euro crisis – POLITICO(https://www.politico.eu/article/france-debt-trouble-memories-euro-crisis/)
- [3]French bonds lead euro zone yields higher | Reuters(https://www.reuters.com/business/french-bonds-lead-euro-zone-yields-higher-2026-10-21/)
- [4]France Bond Risk Gauge Nears 160 Basis Points, Hits 15-Year High - Bloomberg(https://www.bloomberg.com/news/articles/2026-10-21/french-bond-risk-gauge-nears-160-basis-points-hits-15-year-high)
- [5]Franklin Templeton warns: Eurozone debt crisis could be worse than 2012(https://en.forexclub.pl/Franklin-Templeton-warns-eurozone-debt-crisis-could-be-worse-than-2012/)