CoreWeave's revenue beat comes with a $1.1 billion quarterly interest guide and a cash balance of $4.12 billion
CoreWeave beat revenue and margin estimates while guiding interest expense to about $1.1 billion for the next quarter and lifting capital-expenditure plans. The gain is contracted power and a $132.5 billion backlog; the cost is a liability stack that $4.12 billion of cash cannot fund. Credit prices already discount that gap; the 10-Q, not the headline beat, is the record that confirms it.
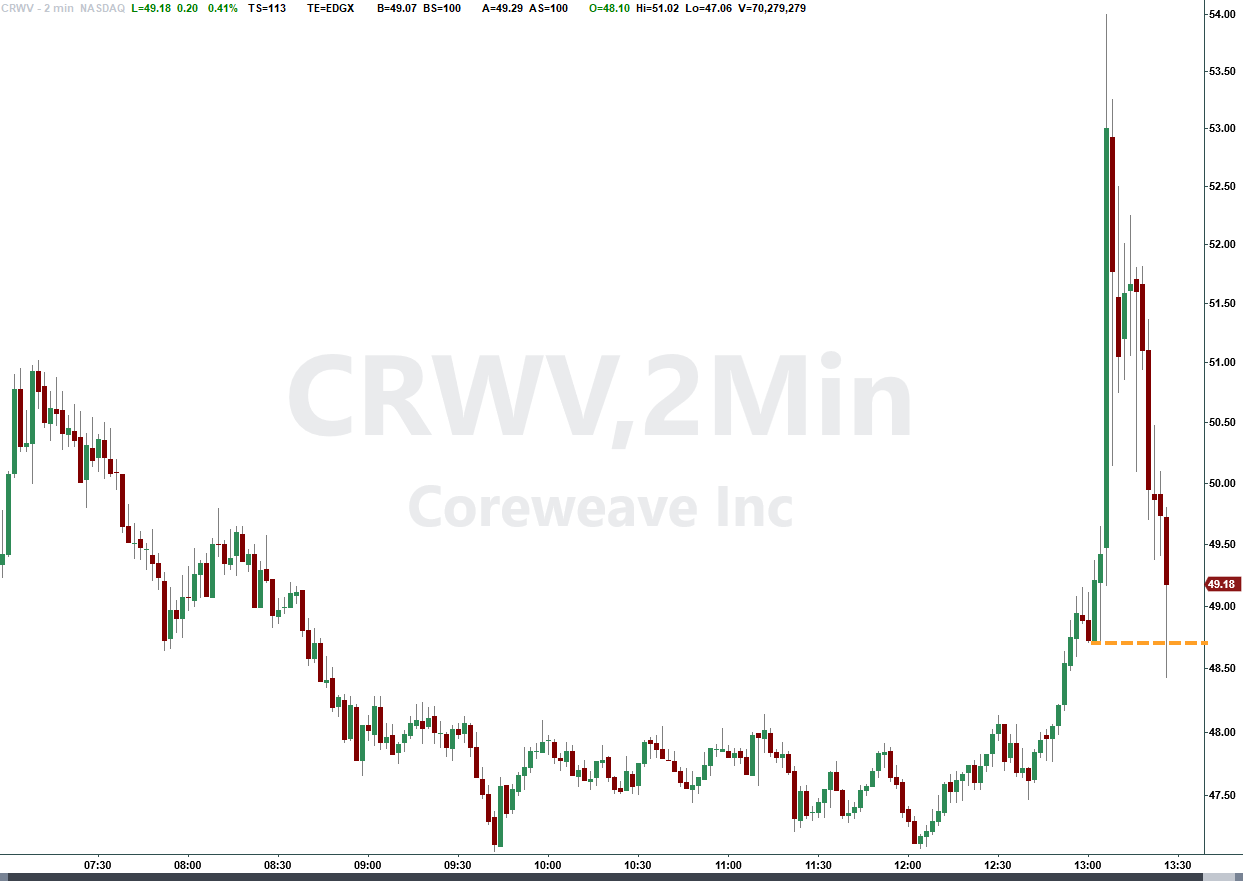
CoreWeave, the GPU cloud operator, reported third-quarter revenue of $3.66 billion, up 168 percent from a year earlier, with adjusted EBITDA of $2.26 billion. Management raised full-year revenue guidance to $13.0–$13.3 billion and said it would pull capital spending forward, lifting the low end of the expenditure range to $37 billion. In the same outlook it guided fourth-quarter interest expense to $1.05–$1.15 billion. Equity initially rose; the move faded once the liability line was read against the income line.
Secondary coverage put liabilities at $87.46 billion and said debt rose $11.8 billion in the quarter, alongside a separate debt figure near $47 billion. Cash fell to $4.12 billion from $5.52 billion. Quarterly interest expense was $846 million. The 9.75 percent 2031 notes were quoted above a 15 percent yield, with CDS above 1,100 basis points. Those are market descriptions, not the filing. The 10-Q fixes gross debt, cash versus non-cash interest, maturities, and customer concentration. Until that exhibit is read, the debt total and the year labels in the secondary piece remain claims.
The incentive split is the story the beat obscures. Large cloud buyers, named in CoreWeave's registration statement, contract for GPUs and power without carrying the full build. CoreWeave's gain is backlog of $132.5 billion, up from $104.2 billion, plus active power above 1.7 gigawatts and contracted power above 4.6. The cost is duration: coupons are current; utilization and permits are not. One of 45 data-center ballot measures went the industry's way in the week described, a constraint on the asset securing the debt. Hyperscalers funding capex from operating cash do not share that refinancing clock.
What follows is whether contracted revenue converts before the interest bill compounds. About $1.1 billion of quarterly interest is roughly $4.4 billion a year if sustained, against $4.12 billion of cash and capex guided from $37 billion. That gap is closed by new debt, customer prepayments, or equity, not by the beat. The documents that decide it are the 10-Q interest footnote, the funding bridge, and any covenant or springing maturity. If cash interest holds near the guide and liquidity falls without new capital, equity and credit narratives diverge. The counterparty that matters next is the lender.
Sources (3)
- [1]CoreWeave Pops On Beat And Raise... Then Guides To A $1.1 Billion Quarterly Interest Bill As Debt Hits $47 Billion(https://www.zerohedge.com/markets/coreweave-pops-beat-and-raise-then-guides-11-billion-quarterly-interest-bill-debt-hits-47)
- [2]CoreWeave Investor Relations(https://investors.coreweave.com/)
- [3]SEC EDGAR full-text search for CoreWeave filings(https://www.sec.gov/edgar/search/#/q=%22CoreWeave%22)