Banks test a higher Anthropic range while book coverage remains a sales claim, not a clearing price
Reported demand for Anthropic's IPO is being used to justify a valuation above roughly $1.4 trillion, but oversubscription measures allocation interest, not aftermarket support. The unpriced variable is state control of advanced compute and the power and permitting constraints on hyperscaler capex. Until lockups and related-party cloud terms are in the filing, banker coverage claims are not a price.
Anthropic's bankers, led by Goldman Sachs and Morgan Stanley according to the Financial Times as relayed by ZeroHedge, are reported to be testing demand above a marketed range of $70 to $78 for 825 million shares under the ticker ANT. Bloomberg, cited by the same account, says the book is multiple times covered. The company is described as seeking up to $90.4 billion via the IPO plus a private placement, with a fully diluted valuation near $1.4 trillion and some bankers arguing for more than $1.5 trillion. Those figures are secondary-market reports, not a quotation from the S-1 text itself.
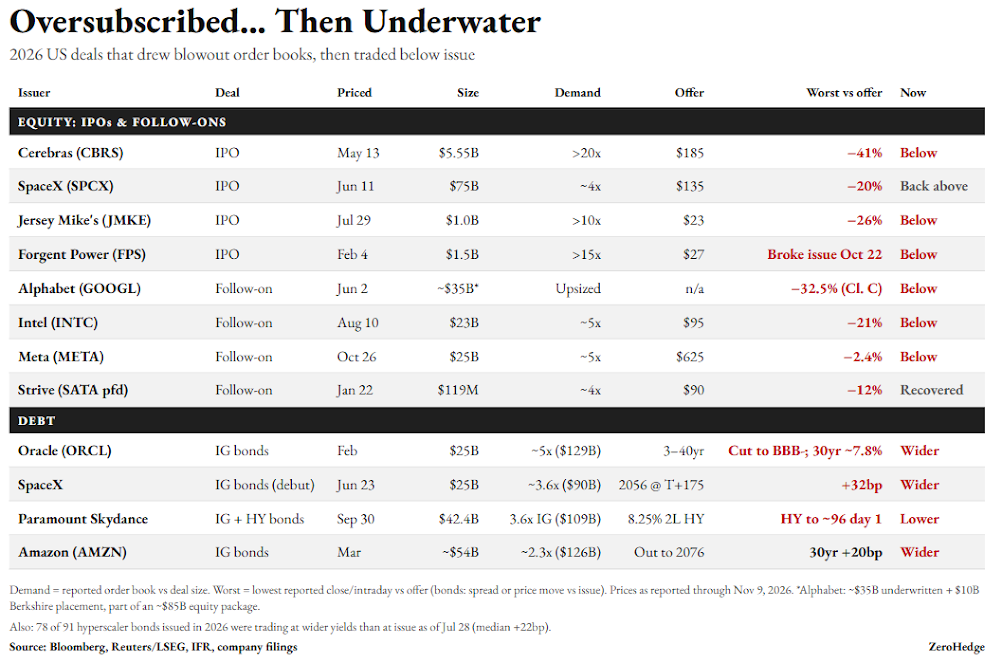
Oversubscription is a distribution fact, not a price forecast. Klarna and StubHub drew heavy books and then traded below their offers, a pattern ZeroHedge uses to discount the headline. The comparison is only partly apt. Debt deals from Oracle and Amazon that were oversubscribed and then saw yields rise measure a different buyer: credit funds marking spread, not equity accounts marking growth. Equity books can be inflated by accounts that bid for allocation and sell on the open. Without the SEC filing's use-of-proceeds, lockup schedule, and cornerstone terms, coverage multiples are not evidence of aftermarket support.
The figure equity desks are not pricing cleanly is the state's role in the cost curve. Anthropic's distribution rests on Amazon and Google cloud commitments and on Nvidia supply still subject to US export controls aimed at slowing Chinese access to advanced accelerators. A valuation above $1.4 trillion assumes that advantage holds and that hyperscaler capex clears power and permitting constraints. Jack Selby told Bloomberg TV a weak debut would be the worst outcome for the AI trade. That is a positioning statement, not a finding. Issuers gain cash and an acquisition currency; public buyers hold the residual risk.
What the oversubscription narrative omits is the counterparty on the other side of the book. Strategic holders already inside Anthropic do not need the IPO to express a view; the marginal buyer does. If the lead banks lift the range, they transfer scarcity from the issuer to the aftermarket and raise the price long-only accounts must defend. Moratorium talk should be logged as statements by officeholders, not as enacted national policy. The next record that matters is the final range and the S-1 amendment on lockups and related-party cloud contracts. Until those are on EDGAR, coverage multiples remain a sales claim.
Sources (3)
- [1]ZeroHedge: Anthropic bankers push higher IPO valuation(https://www.zerohedge.com/markets/anthropic-bankers-push-higher-ipo-valuation-thiel-capitals-jack-selby-warns-weak-debut)
- [2]BIS: Commerce controls on advanced computing items(https://www.bis.gov/press-release/commerce-strengthens-restrictions-advanced-computing-semiconductors-semiconductor-manufacturing-equipment-supercomputing)
- [3]Amazon: additional investment in Anthropic(https://www.aboutamazon.com/news/company-news/amazon-invests-additional-4-billion-in-anthropic)