New-vehicle prices hit a record $51,109 as monthly payments and long loans also set highs
Kelley Blue Book put the average new-vehicle price at a record $51,109 in October 2026, while Edmunds recorded a $787 average new-car payment and a record share of 84-month loans. Credit data show flat serious delinquency on all auto loans and much higher stress in subprime ABS, not a documented lender collapse.
Documented: Kelley Blue Book, a Cox Automotive brand, reported that the average transaction price for a new vehicle in the United States reached $51,109 in October 2026, up 1.3% from a revised $50,460 in September and 2.1% from October 2025. That was the first time the series topped $51,000 and above the previous record of $50,614 in December 2025. Average MSRP rose 2.4% year over year to $52,933. Cox said the gain was driven in part by what buyers chose, not only by list-price inflation: midsize SUVs (ATP $50,570) and full-size pickups (ATP $67,912) pulled the industry average up, while compact cars averaged $28,030 and compact SUVs $37,895. The 2.1% annual ATP increase was below Cox’s longer-run October average of 3.6%. Incentives averaged about 6.8% of ATP, or roughly $3,490, still below pre-pandemic norms. Analysts at Cox have noted that the headline average does not mean most buyers paid $51,000; mix toward expensive trucks and SUVs skews the mean.
Documented, separate series: Edmunds’ third-quarter 2026 financing data, based on financed purchases, put the average new-car monthly payment at a record $787, up from $777 in the prior quarter and $756 a year earlier. The average amount financed hit a record $44,664. Average APR was 7.0%. A record 21.2% of financed new-car buyers committed to payments of $1,000 or more. A record 25.5% took loans of 84 months or longer, up from 21.8% a year earlier. Average lifetime interest on those loans was about $9,938. Used-car payments averaged about $582. Edmunds’ head of insights, Jessica Caldwell, described buyers as adapting by allocating more of household budgets to vehicles, stretching terms, and shopping financing, rather than leaving the market.
Documented, related stress: Edmunds has also tracked rising negative equity on trade-ins. In the third quarter of 2025, 28.1% of trade-ins toward new-car purchases were underwater, with an average negative equity of $6,905, then a record. By the fourth quarter of 2025, that share was 29.3% and average negative equity was $7,214, with 27% of underwater trade-ins carrying $10,000 or more. Buyers who rolled negative equity into a new loan faced much higher payments than the industry average.
On credit performance, the New York Fed’s November 10, 2026 household-debt report put auto loan balances at $1.73 trillion after a $21 billion quarterly increase. The flow into serious delinquency (90 days or more) on auto loans was about 3.02% in the third quarter of 2026, essentially flat versus 2.99% a year earlier. Aggregate household debt in some stage of delinquency rose to 5.0%. The Fed described overall credit trouble as consistent with pre-pandemic conditions and well below the financial crisis, not as a system-wide break. Separately, Fitch’s index of subprime auto loans packaged into asset-backed securities showed much higher stress than prime: a January 2026 reading of 6.90% at least 60 days past due was reported as a record under the methodology then in effect, with later readings still elevated (about 6.13% in July 2026) after a methodology revision. That index covers securitized subprime pools, not all U.S. auto loans. Prime ABS delinquency remained under 0.5%.
Claimed, and only partly supported: commentary that record stickers and payments signal a broad collapse in middle-class purchasing power or an imminent systemic failure of auto lenders goes beyond what Cox, Edmunds, the New York Fed, and Fitch have published. What those sources document is a two-track market. Higher-income buyers are still absorbing large SUVs and pickups and are stretching terms to keep payments workable. Lower-income and subprime borrowers show clearer payment stress inside securitized pools. Long loans also slow equity buildup, which is consistent with the rise in underwater trade-ins Edmunds has measured—not a forecast of lender insolvency.
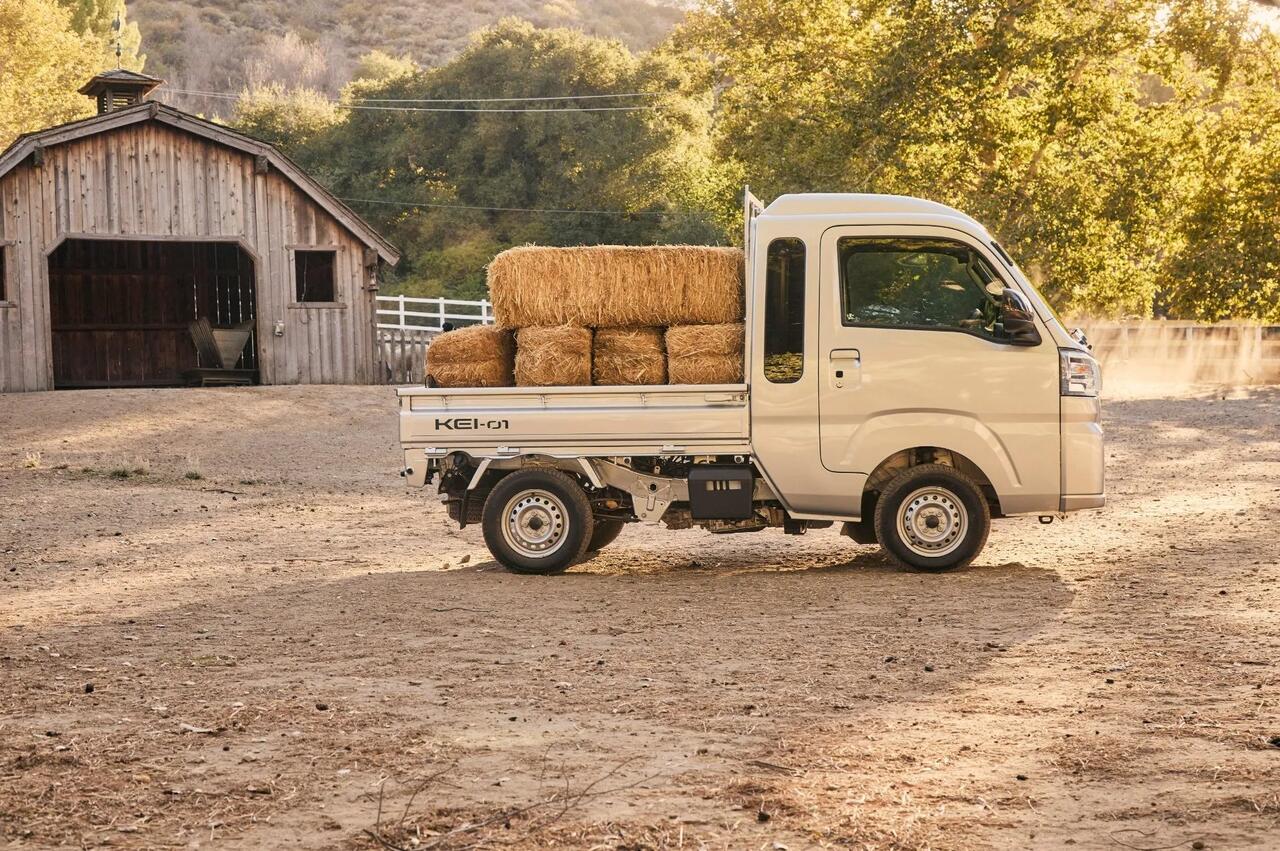
Documented industry response, limited in scale: On November 10, 2026, Toyota said it will assemble an ultra-compact KEI-01 utility truck at its Princeton, Indiana plant in the second half of 2027, investing $34 million and adding about 50 jobs, and relaunch the Scion name for a fleet-focused pilot. Reuters reported a 660cc engine, right-hand drive, and a 25 mph top speed under federal low-speed-vehicle rules. Initial distribution is to fleet customers, not mass retail. No U.S. price has been disclosed. It is a small, regulated niche product, not a documented substitute for the $50,000-class vehicles that dominate current transaction prices.
Speculated: Whether stretched 84-month loans, negative equity, and subprime ABS losses will feed back into tighter credit and lower new-vehicle demand is not established by the October price report. The documented pattern so far is resilience at the top of the mix, adaptation via longer loans, and concentrated stress below prime.
Households financing a new vehicle are paying record monthly amounts and, in a growing share of deals, locking in loans of seven years or more, which slows equity and raises total interest. The documented strain is sharpest among subprime borrowers in securitized loans, while the overall auto-loan book has not shown a comparable jump in serious delinquency.
Sources (8)
- [1]Kelley Blue Book Report: Average New-Vehicle Prices Top $51,000, Reach Record High in October(https://www.coxautoinc.com/insights/oct-2026-atp-report/)
- [2]Car loans are getting longer as monthly payments hit record highs(https://www.cnbc.com/2026/10/06/car-loans-are-getting-longer-as-monthly-payments-hit-record-highs.html)
- [3]Underwater and Sinking Deeper: Edmunds negative equity press release(https://www.edmunds.com/industry/press/underwater-and-sinking-deeper-the-average-amount-owed-on-upside-down-auto-loans-climbed-to-an-all-time-high-of-6905-according-to-edmunds.html)
- [4]Falling Underwater on a Car Loan Is Becoming More Common and Expensive Than Ever(https://www.edmunds.com/car-news/edmunds-q4-2025-insights-report.html)
- [5]Household Debt Increased Moderately; Delinquency Transition Rates Remain Flat(https://www.newyorkfed.org/newsevents/news/research/2026/20261110)
- [6]NY Fed finds troubled debt levels ticked up in third quarter(https://www.reuters.com/world/ny-fed-finds-troubled-debt-levels-ticked-up-third-quarter-2026-11-10/)
- [7]Fitch: Stress in subprime surfaces through auto ABS trends(https://www.autoremarketing.com/subprime/fitch-stress-in-subprime-surfaces-through-auto-abs-trends/)
- [8]Toyota to bring mini trucks to US market(https://www.reuters.com/business/autos-transportation/toyota-bring-mini-trucks-us-market-2026-11-10/)