Meta Reports $64.6 Billion Q3 Revenue Beat but Flags Rising AI Serving Costs
Meta delivered a revenue and EPS beat in Q3 but the market focused on CFO warnings about escalating AI serving costs and negative free cash flow. The data show impression growth slowing while capex commitments rise, exposing a classic trade-off between long-cycle infrastructure bets and near-term profitability. Primary filings confirm the cost pressure is structural rather than transitory.
Meta's core advertising business showed mixed signals. Ad impressions rose only 10 percent year-over-year against an expected 12.3 percent, while average price per ad increased 14 percent. Family of Apps operating income fell 31 percent to $17.12 billion, and the company booked a $9.9 billion legal charge that compressed operating margin to 20 percent from 40 percent a year earlier. Reality Labs revenue missed estimates at $443 million.
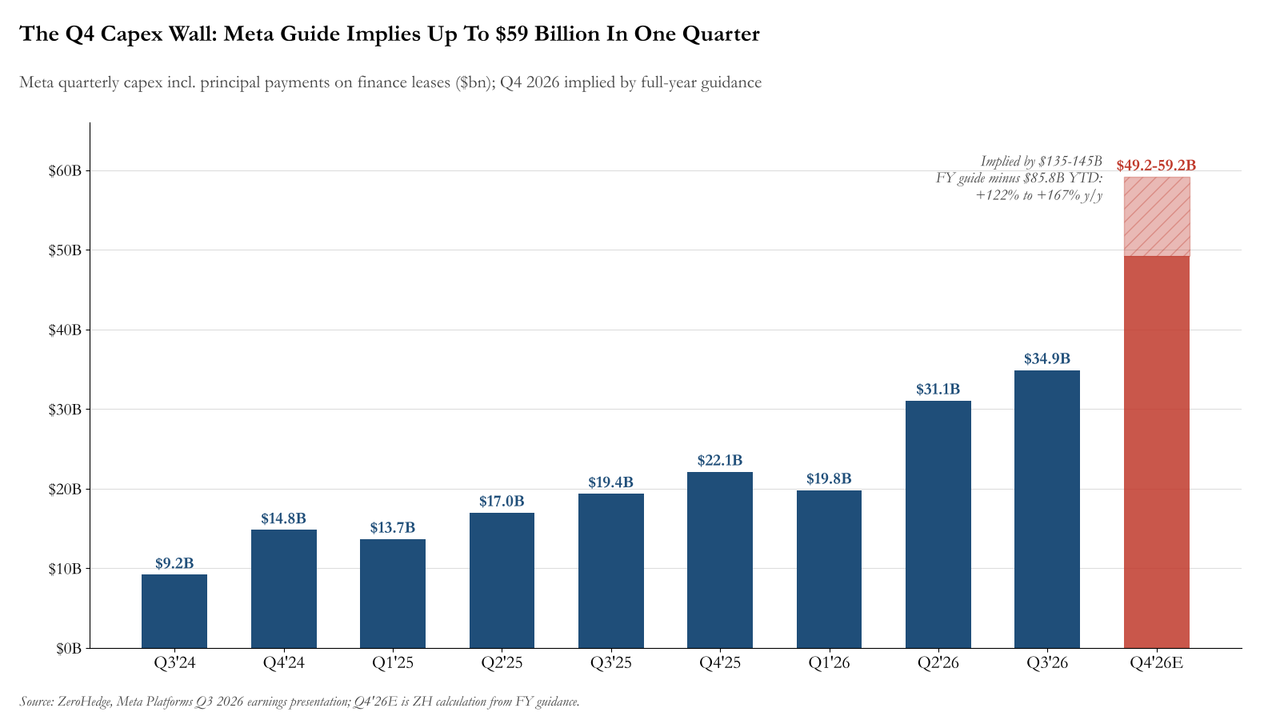
The earnings release and subsequent call revealed a structural tension between product ambition and cash generation. Meta lifted its full-year expense outlook and confirmed that expanding Llama and agent usage will require sustained infrastructure outlays. Free cash flow turned negative in the quarter, aligning Meta with Amazon's recent trajectory where AI-related capital spending outpaces near-term monetization. The 2026 capex guide of roughly $59 billion is now viewed as a floor rather than a peak.
Market positioning and peer comparisons underscore the stakes. At 19 times forward earnings Meta trades at a discount to most Magnificent Seven peers, yet investors have punished prior instances when capex commentary exceeded Street models. Primary documents from Meta's investor site and the Q3 10-Q show no change in the company's stated AI priority, only acknowledgment that compute efficiency gains of tenfold will still leave absolute costs higher.
Next steps hinge on whether Meta can convert user engagement into higher-margin AI revenue before the capex cycle widens the cash-flow gap further. Analysts will watch December guidance and any 2027 spending signals for confirmation that efficiency improvements offset the documented cost trajectory.
Meta: 2026 capex will exceed $65 billion as confirmed in the next earnings release.
Sources (2)
- [1]Primary Source(https://investor.atmeta.com/financials/quarterly-results/default.aspx)
- [2]Supporting Source(https://www.sec.gov/Archives/edgar/data/1326801/000132680124000045/meta-20240930.htm)