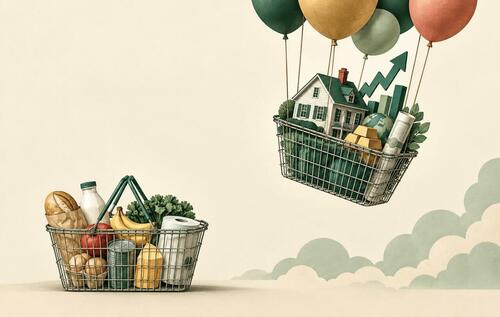
CPI's Blind Spot: How Excluding Asset Prices Masks the True Cost of Living and Widens Wealth Gaps
Credible sources confirm CPI deliberately excludes asset prices like homes and equities, using OER for shelter instead. This has hidden rapid appreciation in stocks (~9-11% annualized since 1995) and homes (outpacing CPI), contributing to affordability crises and inequality not captured in official inflation figures used by the Fed.
Official inflation metrics like the Consumer Price Index (CPI) systematically exclude the prices of major assets such as homes and stocks, a methodological choice rooted in measuring only consumption goods and services rather than investments. The U.S. Bureau of Labor Statistics confirms that CPI covers purchases for current use by households and explicitly omits stocks, bonds, and real estate as investment items. For housing, it relies on owners' equivalent rent (OER)—an estimate of rental value—rather than purchase prices, making shelter about 35% of the index but detached from asset appreciation.
This exclusion has grown consequential amid decades of divergent trends. Since the mid-1990s, the S&P 500 has delivered annualized total returns near 9-11%, while the S&P CoreLogic Case-Shiller U.S. National Home Price Index has risen substantially faster than CPI's roughly 2.6% annual pace over similar periods. Median existing-home prices reached approximately $408,000 in 2024 against median household incomes of $83,000–$87,000, pricing many out of ownership and exacerbating the renter-owner wealth divide.
Academic and policy analyses, including a 2002 SSRN paper by Bryan, Cecchetti, and O'Sullivan, highlight an 'excluded goods bias' in CPI from omitting asset prices, estimating a downward bias of about 0.25 percentage points annually, with housing contributing most. BLS documentation traces the OER approach to 1983, separating consumption services from investment elements to align with cost-of-living index theory. Critics note this leaves monetary policy—often tied to CPI or PCE targets—less attuned to asset inflation fueled by liquidity expansions post-1990s.
The result is a statistical picture that understates pressures on younger or asset-poor households while amplifying gains for owners, a dynamic visible in record wealth gaps and housing affordability challenges documented across Census and Fed-linked data.
Economists and policymakers: Persistent CPI-asset divergence will sustain debates on alternative inflation measures, potentially influencing Fed targeting frameworks and exacerbating generational wealth divides absent policy shifts.
Sources (8)
- [1]Concepts: U.S. Bureau of Labor Statistics(https://www.bls.gov/opub/hom/cpi/concepts.htm)
- [2]Common Misconceptions about the Consumer Price Index: Questions and Answers(https://www.bls.gov/cpi/factsheets/common-misconceptions-about-cpi.htm)
- [3]Treatment of owner-occupied housing in the CPI(https://www.bls.gov/cpi/additional-resources/treatment-owner-occupied-housing.htm)
- [4]Asset Prices in the Measurement of Inflation (SSRN)(https://papers.ssrn.com/sol3/papers.cfm?abstract_id=296544)
- [5]U.S. Case Shiller National Home Price Index 2000-2026 | Statista(https://www.statista.com/statistics/199360/case-shiller-national-home-price-index-for-the-us-since-2000/)
- [6]S&P 500 Returns since 1995(https://dqydj.com/sp-500-historical-return-calculator/)
- [7]U.S. Median Home Prices 1968–2024(https://housingalmanac.com/home-prices.html)
- [8]Income in the United States: 2025 - Census.gov(https://www.census.gov/library/publications/2026/demo/p60-289.html)