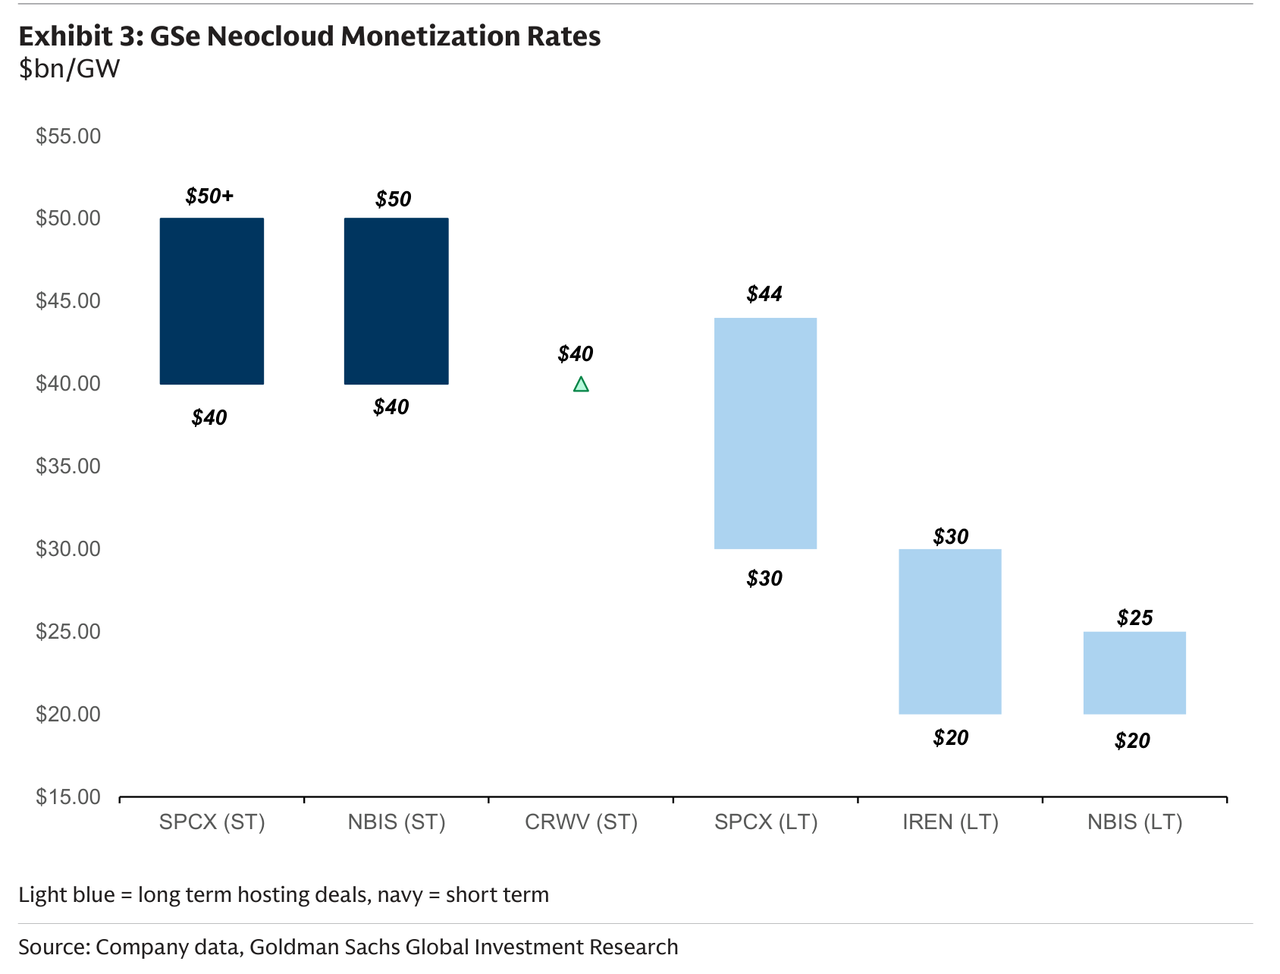
Short-Term Neocloud AI Compute Rents Hit $40-50 Billion per Gigawatt Against $12 Billion Hyperscaler Hurdle
Short-term AI compute leases priced four times above hyperscaler return requirements reveal a temporary scarcity premium rather than sustainable revenue. Contract structure and operator disclosures indicate most revenue remains cancellable quarterly. The mismatch between spot rents and long-term utilization forecasts creates refinancing and valuation pressure once new capacity arrives.
Sustained capex at current scale requires either hyperscaler margins to rise toward neocloud levels or short-term rents to compress toward the $12 billion floor. Neither outcome is visible in operator guidance. The next inflection will occur when additional GW-scale capacity from announced builds reaches online status in 2025, testing whether demand remains elastic at lower rates. Absent acceleration in paid inference workloads, the current term premium will erode as supply balances.
Eric Sheridan: Average realized revenue per GW will fall below $25 billion by Q4 2025 once 2025 capacity additions exceed committed short-term demand.
Sources (3)
- [1]Goldman Sachs SpaceX Q3 Preview(https://www.goldmansachs.com)
- [2]Deutsche Bank Got Compute Note(https://www.db.com)
- [3]IREN and Nebius Capacity Disclosures(https://www.sec.gov)